
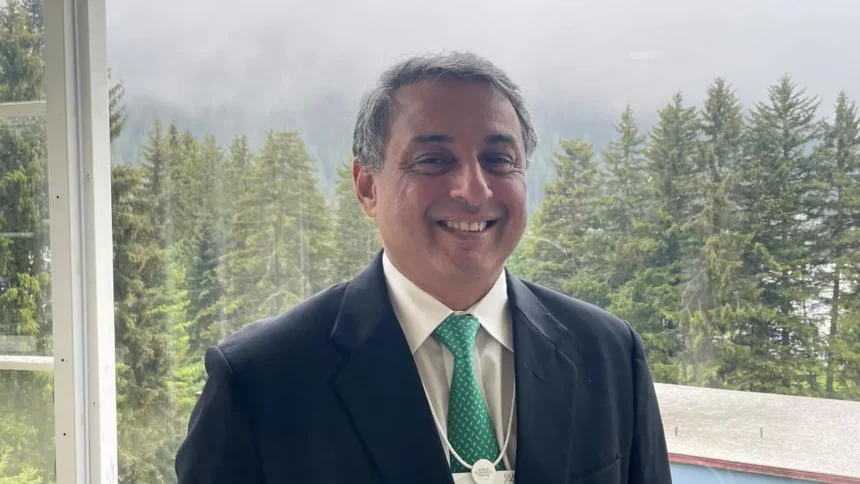
Tata Steel has posted better financials in the September quarter despite challenging global headwinds. TV Narendran, CEO and Managing Director of the company, spoke to businessline on the future outlook for steel prices and input costs, expansion plans, and the challenges facing its European operations.
Edited excerpts:
What led to the fall in EBITDA sequentially?
In India, steel prices were lower in Q2 compared with Q1. Prices started recovering only in September, while July and August witnessed lower prices. Our Q2 realisations were about ₹1,500 per tonne lower than in Q1. Volumes were also not significantly higher, while costs increased due to the impact of the Gulf conflict.
We faced an impact of around ₹1,400 crore on costs, including higher consumables, freight and insurance expenses. Consequently, EBITDA per tonne was squeezed in India. The Netherlands performed better than Q1 in terms of EBITDA per tonne. The UK, however, was weaker because we could not sell the volumes as planned. A large quantity of imports entered the country before the government changed its trade policy. These stocks need to be consumed before domestic producers can regain volumes. While margins improved in the UK, lower volumes affected overall performance.
Finance costs have also increased substantially. What explains the rise?
Part of the increase is attributable to mergers and acquisitions, including the controlling stake acquired in TM International Logistics, and the leases that have come onto our balance sheet. Net debt also increased during the quarter from about ₹82,000 crore to ₹90,000-91,000 crore.
In India, we paid dividends, while our Netherlands and UK operations carried higher inventories and working capital. These are largely temporary factors, and we expect the working capital to normalise in Q3.
Steel prices have increased in recent weeks. Do you expect the current levels to be sustainable?
Prices appear to be close to their peak at the moment, but we expect them to remain strong.
In India, we expect realisations to be about ₹3,500 per tonne higher in Q3 than in Q2, reflecting average prices during the quarter. In the UK, we expect realisations to improve by about £30 per tonne. In the Netherlands, product-level realisations are expected to increase by about €30 per tonne. However, overall realisation could be around €11 per tonne lower because we will be liquidating some slabs accumulated during the previous quarter, which will affect the product mix.
What is your outlook for coking coal and other input costs?
We expect our average coking coal cost of consumption to be about $15 per tonne higher in Q3 compared with Q2. The Gulf conflict has also increased the cost of consumables in India and gas prices in Europe. Freight and insurance costs continue to remain elevated, although forward freight rates have declined. If oil prices remain below $100 per barrel, there could be some relief, but it is difficult to predict how long that will last.
Tata Steel has spent around ₹6,800 crore on capital expenditure in the first half. What is the outlook for the full year?
We had guided for capital expenditure of around ₹20,000 crore for the year, and we expect to be close to that figure. Of this, about ₹15,000 crore will be invested in India, with the balance going towards our overseas operations.
Are you confident of achieving the targeted annual cost savings of ₹7,000 crore this fiscal year?
The second half should be significantly better than the first half. We could not achieve the planned savings in H1 largely because of volume losses and operational instability at Kalinganagar and Meramandali (both in Odisha). When volumes decline, savings achieved at the operational KPI level do not translate into the expected rupee benefits.
We expect H2 to be better and are working towards the annual target of ₹7,000 crore, although achieving it will be challenging.
Are you expecting a cost overrun in the UK electric arc furnace project?
The electric arc furnace is expected to be ready by March 2028. However, the supply of electricity from the national grid is taking longer than originally planned. Full electricity supply is now expected only around March 2029.
In the interim, we expect to receive temporary power to undertake testing and other activities. This delay has implications for project costs and other aspects. We are discussing the issue with the government to find a solution that works for both sides. We do not want to disclose any numbers at this stage.
What is holding up the proposed restructuring of the Netherlands operations under the joint letter of intent?
The non-binding joint letter of intent, signed in September, has been extended until March 1. Several issues need to be resolved before we can enter into a binding agreement. These include clarity on the treatment of steel slag, restrictions on its utilisation and the proposed closure of our coke ovens.
We have submitted a proposal with a timeline, which regulators are evaluating. There are also issues relating to capital expenditure and the overall business case. Government grants are an important part of the discussions because the business case will require financial support, similar to the UK restructuring. The quantum of grants and the conditions attached to them also need to be worked out. Both sides have agreed to use the extended period to resolve these outstanding issues.
Published on November 12, 2026