
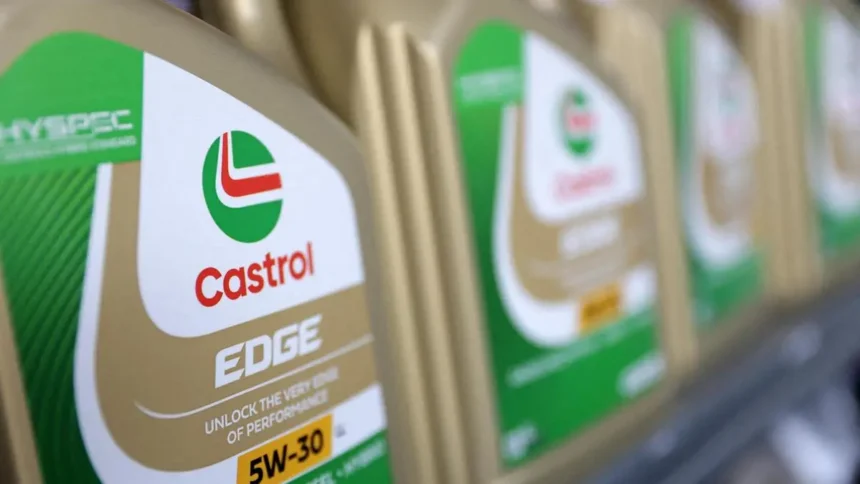
Castrol India’s net profit fell 22.6 per cent to ₹176.37 crore in July–September 2026 from ₹227.80 crore in July–September 2025, as rising raw-material costs and adverse currency movements squeezed earnings ahead of a proposed change in the company’s ultimate ownership.
Revenue from operations rose 27.3 per cent to ₹1,734.72 crore from ₹1,362.75 crore, while earnings before interest, tax, depreciation and amortisation (EBITDA) declined 18.8 per cent to ₹262.04 crore from ₹322.80 crore, according to third-quarter results announced on Saturday. Castrol follows a January–December financial year.
“In a quarter marked by a sharp rise in raw material costs and adverse currency movements, Castrol delivered a resilient performance,” Managing Director Saugata Basuray said in the earnings release.
“Pricing actions taken early in the year helped moderate the impact on margins,” he added.
The deterioration follows management’s warning during its August Q2 earnings call that lower-cost inventory had cushioned profitability and commodity inflation would become more visible in September.
“As communicated in August, we expect the operating environment to remain volatile and inflationary,” Chief Financial Officer Mrinalini Srinivasan said.
“We will act with agility to manage margin pressures through pricing and cost actions, while remaining focused on growing market share across every segment in which we operate,” she added.
The results come as BP prepares to sell a 65 per cent controlling stake in its global Castrol lubricants business to investment firm Stonepeak, in a transaction valuing the business at approximately $10 billion. The deal would give Stonepeak indirect control of Castrol India, in which UK-based Castrol Limited holds 51 per cent.
The proposed change in control has led to a mandatory open-offer process for Indian shareholders. Stonepeak and its partners have proposed acquiring up to 26 per cent of Castrol India’s shares at an initial price of ₹194.04 apiece, representing a potential outlay of approximately ₹4,990 crore.
Castrol India would remain listed unless a separate delisting process is undertaken. Its existing operations are not automatically affected by the proposed ownership change, which remains subject to regulatory approvals. Completion of the global transaction is targeted by the end of 2026.
Raw and packing material consumption surged 70.8 per cent to ₹1,085.86 crore from ₹635.79 crore, lifting material costs to 62.6 per cent of revenue from 46.7 per cent a year earlier.
The EBITDA margin contracted to 15.1 per cent from 23.7 per cent, a decline of approximately 860 basis points. Total expenses increased 41 per cent to ₹1,504.74 crore from ₹1,067.18 crore, outpacing revenue growth.
For January–September 2026, net profit stood at ₹766.25 crore, up 8.6 per cent from ₹705.26 crore a year earlier. Revenue grew 20.3 per cent to ₹5,151.43 crore from ₹4,281.58 crore, while EBITDA increased 11 per cent to ₹1,086 crore.
Compared with April–June 2026 quarter, net profit fell 49.3 per cent to ₹176.37 crore from ₹347.70 crore, while revenue declined 7.3 per cent to ₹1,734.72 crore from ₹1,871.47 crore.
Castrol’s industrial business recorded double-digit volume growth and added 700 customers across automotive and machinery manufacturing, metals, aerospace and sugar industries.
Its distribution network reached approximately 1.67 lakh outlets, including 46,000 rural outlets. Auto-care products were available through about 50,000 physical outlets, while its service network included more than 870 Castrol Auto Service centres and over 1,000 Rural Service Express locations.
Published on October 24, 2026