
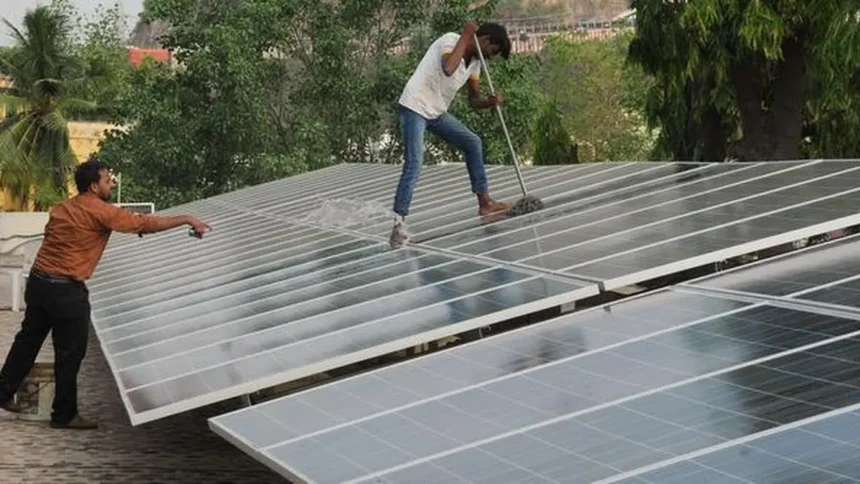
Despite seeing robust demand in FY27, India’s solar module manufacturing sector is expected to face margin pressure given server overcapacity, according to India Ratings and Research.
India’s module manufacturing capacity has reached 228 GW, more than three times the estimated annual requirement of 65-70 GW.
With capacity significantly exceeding demand, factors such as plant utilisation, technology, customer access, liquidity and returns on capital will become more important than the capacity announced by companies, the ratings agency said.
The report also said that imported modules remain cheaper than domestic alternatives by as much as $0.2-$0.3 per watt even including customs duty. Consequently, the implementation of the Approved List of Models and Manufacturers List-II will be central to absorbing domestic cell capacity, it added.
Ind-Ra expects the industry’s profit pool to gradually shift from modules to cells and further upstream to wafers and ingots. This is likely to favour well-capitalised and integrated manufacturers while low-debt module makers with established customer channels and high asset utilisation could remain viable even at lower margins.
In contrast, highly leveraged greenfield projects and standalone module assemblers dependent on spot-market cells could face greater pressure as the price difference between domestic and imported cells narrows.
“Policy access and integration will increasingly determine market position, but neither guarantees stronger credit quality. As manufacturers move upstream, the ability to preserve return on capital, manage technology transitions, and fund expansion without weakening liquidity will separate sustainable business models from capacity-led growth,” says Bhanu Patni, Director, Corporate Ratings, Ind-Ra.
Published on November 20, 2026