
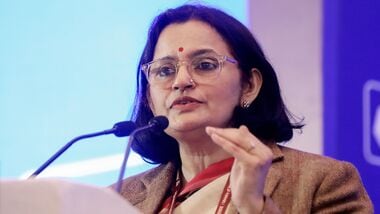
New Delhi: High government borrowing, rising risk premiums and massive investments in artificial intelligence (AI) are pushing up the cost of capital across economies, including for emerging markets like India, economic affairs secretary Anuradha Thakur said on Sunday.
Speaking at a late-evening session of the Kautilya Economic Conclave in New Delhi, Thakur said the defining challenge for economies today is not just how they respond to change, but how effectively they anticipate, adapt to and harness it.
For decades, Thakur said, businesses prioritised cost optimization, just-in-time production and integrated global supply chains.
“Resilience, adaptability, and flexibility now seem to matter equally if not more. But they come with the cost of more capital,” she said. “The ability to remain agile, embrace innovation, and their resistance is, and will remain, critical to sustaining growth and competitiveness.”
Pointing to changes in global financial markets, she said bond markets were assuming a larger share of financing, with government papers alone accounting for more than 80% of global gross domestic product. This has made the global sovereign bond market a key determinant of the cost of capital.
While governments are borrowing large sums, investors are factoring in greater risk premium, thus driving term premia and long-term yields, including in the developed world. This poses a big challenge for emerging economies.
She also dwelt upon the growing relations between global trade and geo-strategic concerns.
“When trade is organized around security and geostrategic concerns, and not comparative advantage, goods and capital move less efficiently, surpluses and deficits become sources of friction, and the price of capital further rises for everyone,” she said.
In this age of flux, the AI investment cycle has added a new dimension. The investment requirements are no longer limited to software or computing but extend to data centres, semiconductors, reliable electricity and transmission capacity, much of which is being financed through debt.
“More investment means greater demand for savings, while higher borrowing means financial markets have to absorb a large supply of it. Global yields, therefore, cannot be understood only in terms of monetary policy and fiscal deficit anymore. The scale of the AI build-out is now part of that story,” she said.
Thakur highlighted robust gross FDI inflows into India and the sectoral pattern of such inflows, stressing that global capital is not simply viewing India as a low-cost production base but as a place to build capacity.
India, she said, drew record gross foreign direct investment inflows of about $97 billion last fiscal, and $29.3 billion in the June quarter.
“This is a show of confidence in the fundamentals that India has demonstrated,” she said.
At the same time, private investments are rising now, after years of concerns about their subdued growth, she said, adding that investment is once again leading growth. Capital formation grew at its fastest pace in more than three years in the June quarter. Private firms are pledging investments in new projects in sectors, such as power, data centres and metals, while bank lending to enterprises is rising.
Thakur highlighted the Indian government’s commitment to fiscal discipline in recent years, which has contributed to macroeconomic stability. The Centre’s fiscal deficit has been cut from 9.2% of GDP in FY21 to a budgeted 4.3% this fiscal year. The fiscal anchor is also moving towards a declining debt-to-GDP ratio, she said. Inflation targeting has kept prices anchored, bad loans in the banking system are at multi-decade lows, foreign exchange reserves remain strong and India has seen several rating upgrades in the past one-and-a-half years.
“Fiscal credibility, price stability and a sound banking system are the foundation for any country that hopes to borrow at a reasonable price when capital is scarce and expensive,” she said.
The government, Thakur said, has embraced reforms with conviction over the past decade. This has helped the economy grow at an average of over 7% in the past three years while preserving macro stability.
She listed out key reforms of the past decade. These include reforms in the banking system and technology infusion, the roll-out of the goods and services tax and the Insolvency and Bankruptcy Code, reduction in the corporate tax rate, decriminalisation of over 190 provisions across laws and new labour codes.
Moreover, the government has consistently raised capital spending, which typically de-risks early-stage, long-gestation projects after which private capital can scale up, she said. The Centre’s capital expenditure (capex) has shot up from about ₹2 trillion in FY15 to a budgeted ₹12.22 trillion for FY27.
Measures, she said, can be announced but credibility that India has earned is gained through sustained efforts.
“So, we can we find that measures can be announced, but credibility that our country has earned is one that is gained through sustained efforts–through physical consistency, discipline, reforms and deregulation,” she said.
“We have followed this path of steady reform, prudent macro-economic management. Like I said, the hope is that the rules of the game will still play out,” she said.