
Tata Trusts proposal to keep Tata Sons private could lead to the merger of its two iPhone manufacturing units.
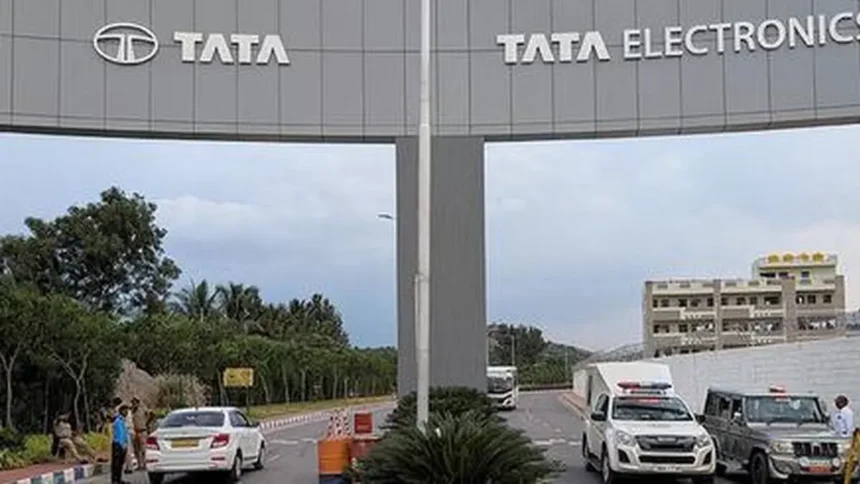
On Monday, Tata Trusts proposed a merger of Tata Electronics Systems Solutions Private Ltd (TESS) and Tata Consulting Engineers (TCE) with Tata Sons to keep the holding company outside ambit of RBI’s non-banking finance company -upper layer category (NBFC-UL).
While TESS (formerly known as Wistron Infocomm Manufacturing India) makes iPhones, TCE provides engineering and consultancy services.
Tata Trusts is hopeful that the merger will keep Tata Sons outside the purview of RBI’s regulatory framework for NBFC-UL. It also believes that new investments by the holding company will not change the status.
Tata Trusts advisor Farokh Subedar said TESS has a turnover of over ₹60,000 crore and an asset size which keeps us below the 90 per cent cap applicable to a core investment company.
TESS owns 60 per cent stake in device maker Tata Electronics Products and Solutions Private Ltd ( formerly Pegatron Technology India Ltd).
Subedar said the company has the right to buy the balance 40 per cent shares.
Noel Tata moots merger of 2 group firms with Tata Sons to keep it private
“ In a year’s time or so once it becomes 100 per cent subsidiary of this particular company (TESS), it can also get merged. It will immediately add another ₹60,000 crore of income,” Subedar told reporters.
Tata Trusts did not respond to queries on steps involved in merger plan and risks involved in the process.
In 2023, Tata group acquired manufacturing facility of Wistron India which had faced labour unrest and plant shutdown. With this acquisition it became the first home grown company to manufacture iPhones in India. In 2025 the group bought 60 per cent stake in Pegatron India’s unit in Tamil Nadu.
TESS which houses both the businesses had a standalone operating revenue of ₹67,542 crore in last fiscal. Its consolidated revenue in FY26 stood at ₹1,26,896 crore.
Subedar said merging TESS and TCE with Tata Sons is the cleanest option but the holding company board can look at other companies as well. The Trusts’ proposal will need approval from Tata Sons board and need a no objection certificate from RBI besides required statutory approvals.
“In my view, the proposed merger of TESS and TCE into Tata Sons will face significant regulatory and governance scrutiny. The immediate issue is RBI approval because the restructuring could potentially alter Tata Sons’ regulatory classification and, consequently, its listing obligation. RBI is likely to examine whether there is a genuine commercial and operational rationale for bringing these businesses into Tata Sons or whether the structure is primarily being used to avoid the consequences of the Upper Layer NBFC framework,” said Sonam Chandwani, managing partner, KS Legal & Associates.
“The Shapoorji Pallonji (SP) Group angle makes the issue even more sensitive. As a significant minority shareholder, SP Group has a strong economic interest in the future structure and liquidity of Tata Sons. While it does not automatically have a legal right to demand an IPO, any restructuring that effectively removes or delays a potential liquidity route could raise questions about whether minority shareholder interests are being adequately protected,” she added.
Published on September 29, 2026