
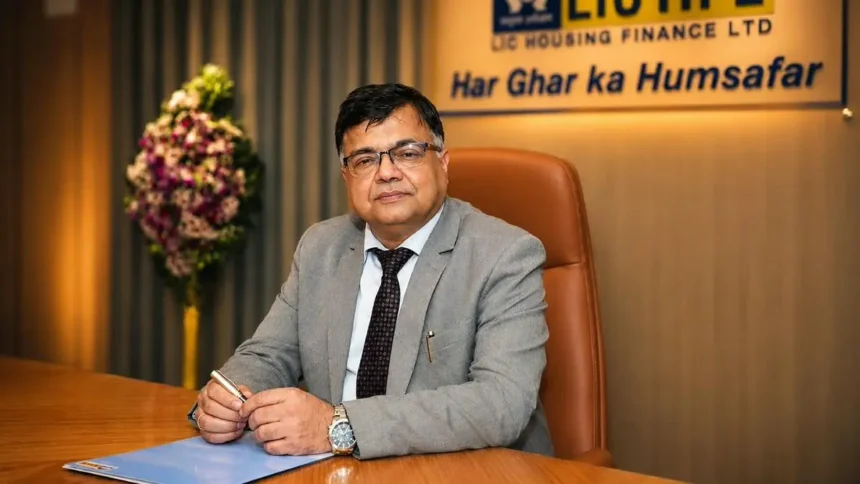
Sandeep Kumar, MD & CEO of LIC Housing Finance, is steering the housing financier’s expansion beyond home loans into project finance, loan against property (LAP) and affordable housing, while keeping its core mortgage business firmly in focus. As the company targets a ₹3.5 lakh crore loan book and around 10 per cent growth in the second half of FY27, Kumar talks to businessline about diversification strategy, market outlook and growth ambitions.
Edited Excerpts:
What contributed to the 11 per cent increase in profit in Q2?
Two months ago, we increased our lending rates by up to 15 basis points. Effective today, we have taken another rate hike of up to 25 basis points across our existing portfolio as well as new disbursements. Our outstanding loan portfolio stands at ₹3.26 lakh crore, reflecting a 4.6 per cent year-on-year growth. Going forward, we aim to grow the portfolio by at least 10 per cent over the next two quarters, to around ₹3.5 lakh crore. For the full year, we are guiding for disbursement growth of 12-14 per cent and a double-digit growth in the loan portfolio.
Any improvement in average ticket size and average age of borrowers?
The average age of our borrowers is around 40-45 years. Typically, a loan account remains with us for seven to eight years. The average ticket size is about ₹32-33 lakh. As we scale up segments such as loan against property (LAP), we expect these metrics to improve further in the coming quarters.
How is your affordable housing segment doing?
We are not meaningfully present in the affordable housing segment at present. To build scale in this business, we need a dedicated operating structure, as our existing model is not best suited to serving this segment efficiently. The proposal is currently before the board, and we expect to have a separate affordable housing vertical in place next year.
Why are you moving beyond salaried borrowers to the self-employed segment when your focus has traditionally been on prime loans? Has the market become saturated?
Historically, more than 80 per cent of our portfolio has come from salaried borrowers. Expanding into the self-employed segment is a conscious strategy, as it offers better margins. We are also increasing our focus on the loan against property (LAP) business and lease rental discounting (LRD). In addition, we are exploring opportunities in project finance, which is a relatively margin-accretive business for us.
What loan mix are you targeting?
Our target is to increase the share of non-home loan products, particularly LAP, to around 20 per cent of the overall portfolio by the end of the year.
Your dominance has been in retail lending. Do you see a bigger shift towards project finance?
We see significant potential in project finance, which is a margin-accretive business and offers us greater diversification. We expect this segment to contribute more meaningfully going forward. Our project finance book currently stands at around ₹10,000 crore, and we are targeting fresh project finance sanctions of around ₹4,000 crore this year. The segment is already showing encouraging signs, with nearly 50 per cent growth during Q2.
Project finance is still a relatively small part of your book. How do you see it evolving?
For the current financial year, we have set a target of 100 per cent growth in the project finance vertical. We are also exploring inorganic growth opportunities. The board has already approved a pool-buying framework. We expect to begin pool-buying activity on a small scale in the third quarter and gradually scale it up with larger transactions in the fourth quarter.
Published on November 1, 2026