
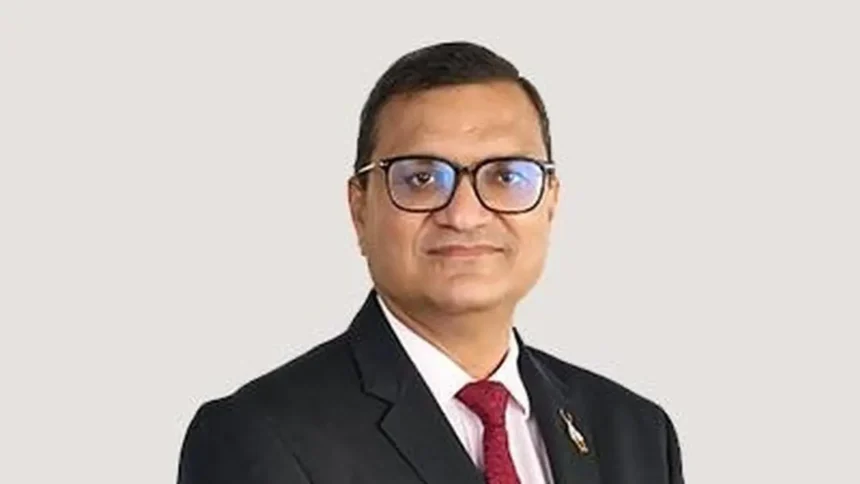
PNB Housing Finance’s loan book grew 19 per cent to ₹95,709 crore in Q2 FY27 but PAT grew just about 6 per cent to ₹617 crore due to higher write-offs. With a strong loan and disbursement growth, the NBFC has hit its target by the second quarter. Ajai Kumar Shukla, MD and CEO, speaks about the road ahead for the company.
Edited excerpts:
You’ve largely completed the realisation journey, which you were talking about. Where is the next growth lever coming from?
New geography expansion will certainly be there as part of the strategy because we’ll keep on growing. As as much as you can group closer to the consumer, your business will grow. And that is why reach is very important.
And a lot of smaller cities are being developed in a larger scale now. A lot of urbanisation, too, is happening, so the growth will be there. We’ll focus on new products like micro housing. We did almost ₹70 crore of business. We also enabled our prime and emerging branches to source more affordable business and that has also helped us in growth in terms of affordable business. So overall, there will be multiple levers. We will also do some some part of construction business, but it will be very miniscule, which will be 3 per cent of our book this year.
Despite improving the credit quality, why has the profit growth lagged at 6 per cent?
The recovery from write-off pool was much bigger in Q2 FY27 compared to Q2 FY26. Since the pool was big, recovery was high. The pool is shrinking now, so it was largely because of that.
The negative rate cost regime may continue for, maybe, till the end of this year. By then it will be normalised. And then, your credit cost will be in the range of 10-15 basis points, which is a normalised rate cost.
Your assets under management (AUM) rose 17 per cent. Does this give you the confidence of continuing the growth trajectory for the next 12-18 months?
I think we are confident and that’s why we have given the guidance also; that our growth for the year will be in 20 per cent in book. So we are still maintaining that.
Overall, retail growth is almost 19 per cent in terms of the book and we had said that it will be in the range of 18-20 per cent.
How has the rate hike impacted or how is it going to impact your business?
As of now, 25 basis points hike has not given any slowdown in the market. I think most of the companies are feeling comfortable in terms of achieving their numbers, what they committed even in October.
The markets are also speaking about a 75-100 bps rate hike for FY27. Will it hit customers?
I don’t think rates will rise 75-100 bps. While there will be some hike depending on the macro scenario because rates have already increased in the industry, I think there will be some hype, but maybe not in that range.
What is the minimum credit score that you’re giving loans to?
Most of my portfolio is above 700. But if the customer is good and because of some other very small old history his score got down to 675-690, and there is a proper justification, then at a very senior-level, [loans] can be allowed.
How do you try to gain market share from banks now?
We compete with them in terms of our capability and the reach in terms of self-employed customer mode. Also, nationalised banks reach the customer directly. NBFCs have to hunt for customers. When you give a good service in the market through an intermediary, they tend to give the next business to you.
But you’re not compromising on underwriting…
We have a team of skilled people who have expertise in self-employed underwriting. So, self employed underwriting could be very simple.
Are you using AI for your operations?
We are using AI in our customer service, in our pre-delinquency management, in our post-customer onboarding, and even pre-customer onboarding. A lot of predictive models are coming in terms of balance transfer-outs because you can do a lot of predictions where the propensity is very high to beat you out. The second tool you can use is in delinquency management, where the customer gives you the payment date and how many follow-ups, so that can save you costs. I need not to put efforts on field because field is a very costly model.
Are you worried about AI rejecting eligible applications ?
See, honestly speaking, as of now, in underwriting, we are using a data science approach, but not much AI. In this business, you need people for legal verification, technical verification, and customer interaction. You need to go and see the setup of the business and then decide whether you can lend to them or not. So there are many things which decide the final outcome of a proposal. AI cannot search in the sub-registrar’s office unless the government digitises property documents historically. They have started doing that, but it’s still it is under progress.
Published on October 29, 2026