
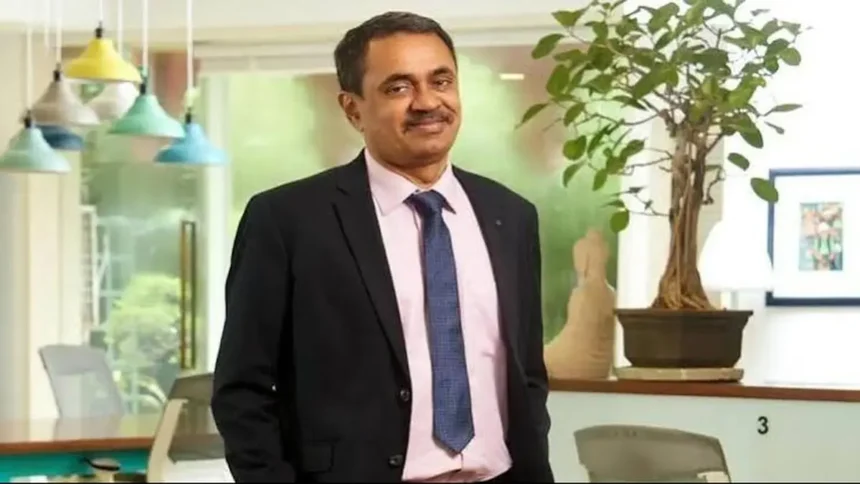
CEAT Ltd is betting on stronger sales, higher capacity utilisation and the transfer of customers from Michelin to turn around its $225-million Camso acquisition, which is still operating at a loss but is moving closer to break-even.
The off-highway tyre business recorded 35 per cent sequential sales growth in the September quarter, while its negative operating margin narrowed from around 10 per cent to 2 per cent. With 85 per cent of Camso customers now serviced directly by CEAT and the remaining 15 per cent expected to transition by December, Executive Director and Chief Financial Officer Kumar Subbiah expects the business to reach EBITDA break-even or a marginally positive margin by March 2027.
In an interview with The Hindu BusinessLine, Subbiah also discusses CEAT’s growth outlook, the impact of repeated tyre price increases on truck operators, rising input costs and its international expansion strategy. Edited excerpts:
How do you see CEAT’s growth shaping up in the second half of FY27?
We have sustained double-digit growth for more than 10 quarters. Earlier, volumes drove growth; now pricing also contributes. International operations and OEMs led the September quarter. After growing over 20 per cent in the first half, maintaining that pace will be difficult because last year’s GST reductions created a higher comparative base. Nevertheless, we expect double-digit growth in both remaining quarters.
Raw-material costs continue to rise. How much more pricing power does CEAT have?
Raw-material costs rose approximately 9 per cent sequentially in Q2 and will increase further in Q3. Price increases have lagged inflation, keeping margins below our internal threshold. OEM prices generally follow quarterly adjustment formulas, while replacement-market increases vary across categories. Freight costs have also risen sharply. We need further pricing action and cost improvements.
Q: Heavy-duty truck tyres can cost ₹15,000 to over ₹55,000. Are higher prices beginning to hurt replacement demand?
Overall tyre prices have risen approximately 12–14 per cent since April. A tyre costing ₹20,000 earlier could now cost ₹22,800–23,000. Commercial-vehicle operators are price-sensitive and may postpone replacements. Repeated increases risk suppressing demand.
Is festive demand providing some relief?
OEM demand remains strong. Tyres supplied during August and September supported vehicles manufactured for October–November festive sales. That momentum continued into October, although replacement demand remains mixed, particularly for commercial-vehicle and passenger-car tyres.
With margins under pressure, will CEAT moderate capital expenditure?
Our FY27 capex guidance remains around ₹1,400 crore because capacity utilisation is high. Debt increased approximately ₹400 crore during Q2, reflecting capital expenditure, dividend payments and additional working capital. It is higher than initially anticipated, partly because of margin pressures.
What has changed operationally at Camso since the acquisition?
The business grew approximately 35 per cent sequentially in Q2, albeit from a low base. Its negative operating margin improved from around 10 per cent to 2 per cent as volumes increased. We now directly service 85 per cent of customers, with the remaining 15 per cent transferring from Michelin during Q3.
What gives you confidence that Camso can break even by March?
The priority is sustaining top-line growth. As production increases, fixed costs can be spread over larger volumes. We expect sequential growth in both Q3 and Q4, taking us towards EBITDA break-even or a slightly positive margin by March 2027.
Why restructure the financing of the Sri Lankan subsidiary?
Approximately $110 million of the acquisition investment related to the Sri Lankan plant. Converting $24.5 million of loans into equity has brought debt-to-equity to around one-to-one. This reduces interest costs and currency exposure while strengthening working-capital support.
How important are exports to CEAT’s next phase of growth?
Standalone exports grew approximately 25 per cent year-on-year and 27.4 per cent sequentially in Q2. Their share of standalone net revenue increased from 19.3 per cent in Q1 to around 20 per cent. Exports are structurally profitable, although passing on raw-material inflation overseas remains challenging. International growth will also help utilise our expanded manufacturing capacity.
Published on October 15, 2026