
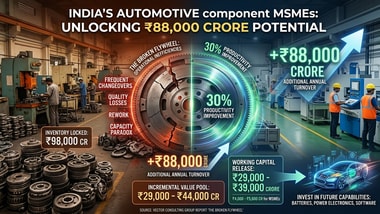
India’s automotive component MSMEs could generate up to ₹88,000 crore in additional annual turnover if they achieve a 30% improvement in productivity, according to a new report by Vector Consulting Group that highlights the scale of operational inefficiencies across the country’s supplier ecosystem.
The study, The Broken Flywheel: Building a Future-Ready Automotive Supply Ecosystem, estimates that automotive componentin turnover. A productivity improvement of 30% across this base could add ₹74,000 crore to ₹88,000 crore in annual turnover, the report said.
After accounting for material costs, the potential incremental value pool could range between ₹29,000 crore and ₹44,000 crore.
The report was launched at the 66th Annual Session of the Automotive Component Manufacturers Association of India (ACMA) and was based on a survey of 21 senior industry executives conducted between July and August 2026.
It found that 95% of industry leaders surveyed believe automotive MSMEs are not investing quickly enough in the capabilities needed for future growth.
The study also identified a gap between the capabilities suppliers will need as the automotive industry evolves and those currently available across the MSME ecosystem.
This challenge is becoming increasingly significant as a larger share of vehicle value shifts towards batteries, power electronics, embedded software and integrated electronic systems.
The report also found that the automotive component industry has around ₹98,000 crore tied up in inventory.
Improved inventory management could potentially release ₹29,000 crore to ₹39,000 crore in working capital, according to the study. Of this, automotive MSMEs could account for a potential release of ₹4,000 crore to ₹5,600 crore.
MSMEs account for around 80% of automotive component manufacturers in India.
Vector Consulting Group saidhave typically reduced inventory by 30% to 40%, based on its implementation experience.
The report argued that releasing capital trapped in inventory could improve the financial capacity of suppliers to invest in technology, engineering and product development.
The study also pointed to what it described as a capacity paradox within the automotive component sector.
Plants are operating at an average utilisation level of 75% to 85%, yet 91% of the respondents surveyed identified capacity as a considerable challenge.
The report attributed this gap partly to frequent production changeovers, quality losses, rework and inefficient material flows, which reduce the productive output companies can extract from their installed capacity.
“The opportunity is not simply about adding more capacity. A significant part of the capacity that Indian companies already have is not being converted into productive output,” said Ravindra Patki, Managing Partner, Vector Consulting Group.
The findings suggest that operational improvements could become as important as new capital expenditure in addressing the sector’s capacity requirements.
According to the report, could create a cycle in which operational improvements release working capital and generate additional surplus.
That surplus could then be deployed towards technology, engineering, product development and other capabilities required to compete in higher-value areas of the automotive industry.
“Unlocking the cash trapped in operations, improving the economics of the existing business, and then channelling the surplus into enhancing capabilities will determine how Indian suppliers grow in the future automotive value chain,” Patki added.
He said the scale of India’s automotive opportunity would depend on how rapidly such capabilities can spread across the supplier ecosystem.
As vehicle manufacturing becomes increasingly dependent on batteries, electronics and software, the report said India’s ability to expand domestic localisation and capture a larger share of global sourcing will depend on whether suppliers can generate enough surplus to continuously invest in new capabilities.
(With PTI inputs)